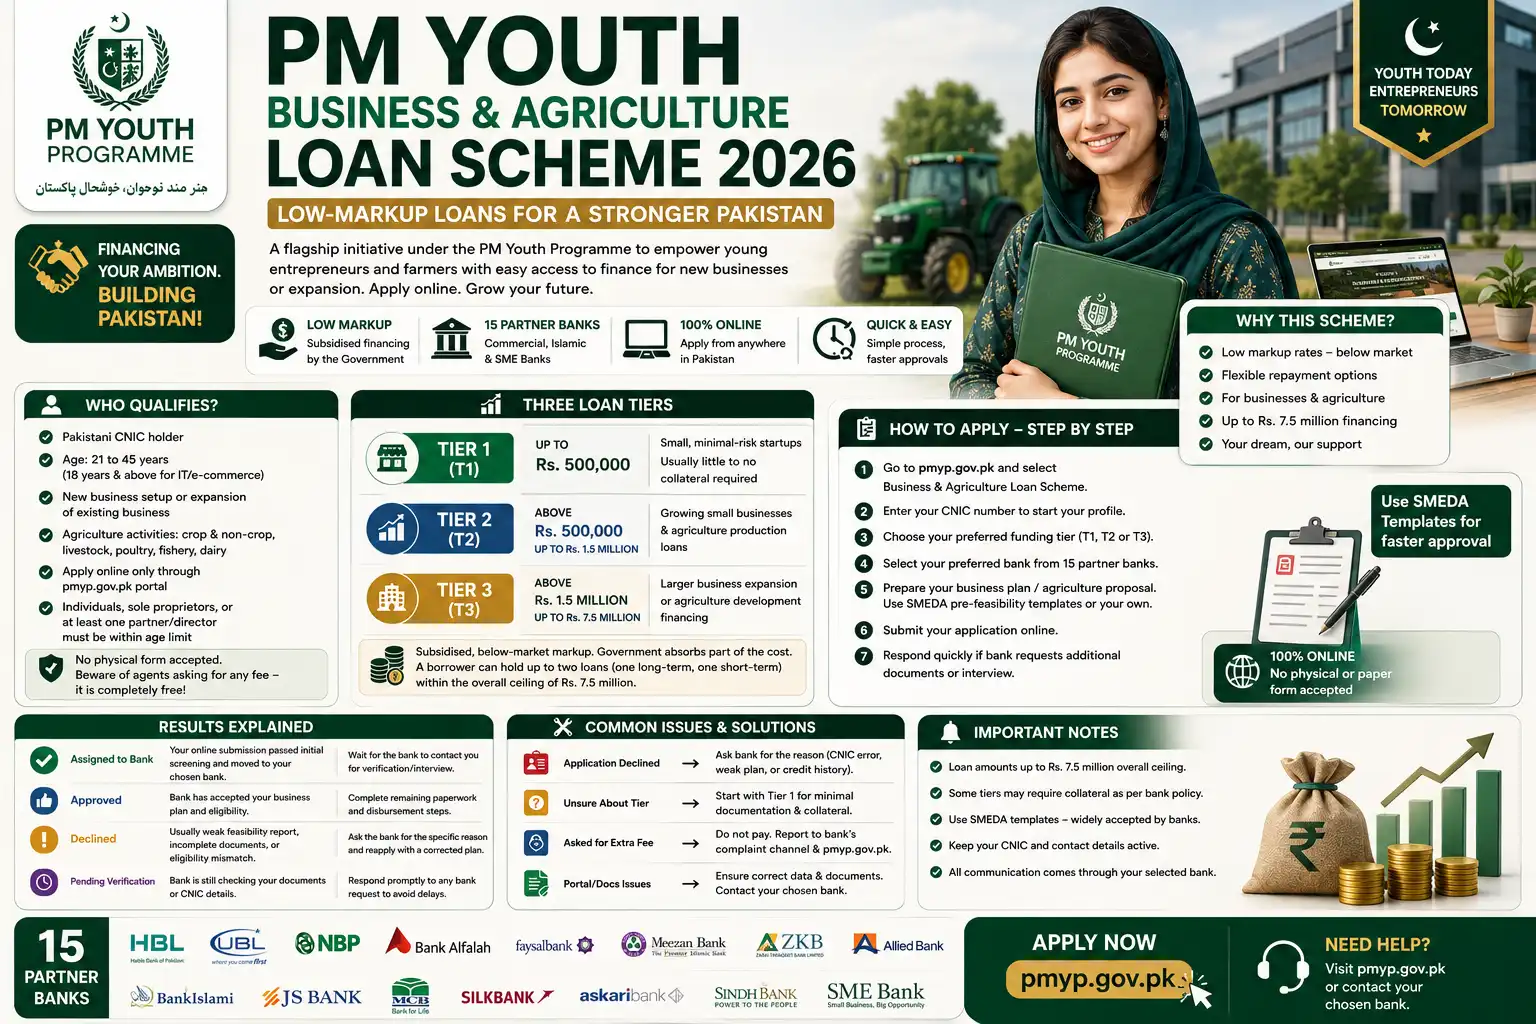
The PM Youth Business & Agriculture Loan Scheme, run under the PM Youth Programme, gives young Pakistanis low-markup financing for new or expanding businesses and agricultural ventures, applied for entirely online and processed by a panel of partner banks. According to the scheme’s official pmyp.gov.pk subdomain, the loan is delivered through 15 commercial, Islamic, and SME banks under three funding tiers, with applicants choosing their preferred bank during the application itself. Eligible applicants are generally aged 21 to 45, with the age floor dropping to 18 for IT and e-commerce ventures. This guide covers eligibility, the three tiers, how to apply, and what to do if your application is declined.
Who Qualifies
| Requirement | Detail |
|---|---|
| Nationality | Pakistani CNIC holder |
| Age (general) | 21 to 45 years |
| Age (IT/e-commerce) | 18 years and above |
| Business type | New business setup or expansion of an existing one |
| Agriculture | Crop and non-crop activities — including livestock, poultry, fishery, and dairy |
| Application channel | Online only, through the scheme’s official portal — no physical form is accepted |
Individuals, sole proprietors, and — for partnerships or companies — at least one owner, partner, or director within the age bracket can apply.
The Three Loan Tiers
| Tier | Loan Amount | Typical Use |
|---|---|---|
| Tier 1 (T1) | Up to Rs. 500,000 | Small, minimal-risk startups; usually little to no collateral required |
| Tier 2 (T2) | Above Rs. 500,000 up to Rs. 1.5 million | Growing small businesses and agriculture production loans |
| Tier 3 (T3) | Above Rs. 1.5 million up to Rs. 7.5 million | Larger business expansion or agriculture development financing |
Loans carry a subsidised, below-market markup rather than a standard commercial rate, with the government absorbing part of the cost — the exact current markup should be confirmed with your chosen bank at application time, since it’s periodically revised. A borrower can generally hold up to two loans at once (one long-term, one short-term) within the overall Rs. 7.5 million ceiling; agriculture borrowers may similarly combine one production loan and one development loan within that same ceiling.
How to Apply — Step by Step
- Go to the scheme’s official application portal, reached through pmyp.gov.pk.
- Enter your CNIC number to start your profile.
- Choose your preferred funding tier (T1, T2, or T3) based on how much capital you need.
- Select the bank you want to process your loan from the approved panel of 15 commercial, Islamic, and SME banks.
- Prepare your business plan or agriculture proposal — SMEDA-provided pre-feasibility templates can be used as a starting point, or you can submit your own.
- Submit your application online; there is no physical or paper form.
- Respond promptly if your selected bank requests additional documents or an interview.
Results Explained
| Outcome | What it means | What to do |
|---|---|---|
| Application assigned to bank | Your online submission passed initial screening and moved to your chosen bank | Wait for the bank to contact you for verification or an interview |
| Approved | Bank has accepted your business plan and eligibility | Complete any remaining paperwork and disbursement steps the bank sets |
| Declined | Usually a weak feasibility report, incomplete documents, or an eligibility mismatch | Ask the bank for the specific reason before reapplying with a corrected plan |
| Pending verification | Bank is still checking your documents or CNIC details | Respond quickly to any bank request — delayed replies slow your own application |
Solve — Common Problems
If your application is declined, ask your bank directly for the reason rather than guessing — common causes include an incorrect CNIC detail, a weak or generic feasibility report, or a poor prior credit history, and each has a different fix. If you’re unsure which tier fits your funding need, starting with Tier 1 keeps documentation and collateral requirements lightest, since it’s designed for first-time, smaller-scale applicants. If a bank or agent asks for an unofficial “processing fee” to speed up your application, that’s not part of the scheme’s design — report it to the bank’s own complaint channel rather than paying it.
In practice, feasibility reports built directly on the scheme’s own SMEDA pre-feasibility templates tend to move through bank review faster than fully custom business plans, simply because reviewers are already familiar with the standard format.
For students weighing this against a laptop instead of a loan, the PM Laptop Scheme is the separate track under the same programme for enrolled university students.
FAQs
What’s the maximum loan amount under this scheme?
Tier 3 goes up to Rs. 7.5 million, though a borrower’s overall exposure across combined loans is generally capped at that same Rs. 7.5 million ceiling.
Do I need collateral for a small loan?
Tier 1 loans, up to Rs. 500,000, generally require little to no collateral, while larger Tier 2 and Tier 3 loans are more likely to need security depending on the bank’s own policy.
Can farmers apply, not just business owners?
Yes. Agriculture is explicitly covered, including crop and non-crop activities such as livestock, poultry, fishery, and dairy, alongside standard business financing.
Is there a minimum education requirement?
General applicants have no fixed minimum education requirement, though IT and e-commerce applicants under the lower 18-year age threshold should confirm their specific bank’s documentation requirements.
Can I apply without choosing a specific bank?
No. You select your preferred bank from the approved panel during the application itself, and that bank processes your loan from that point forward.
What if my application is declined?
Ask your bank directly for the specific reason — usually documentation, feasibility, or credit-history related — and correct that issue before reapplying rather than resubmitting the same application unchanged.