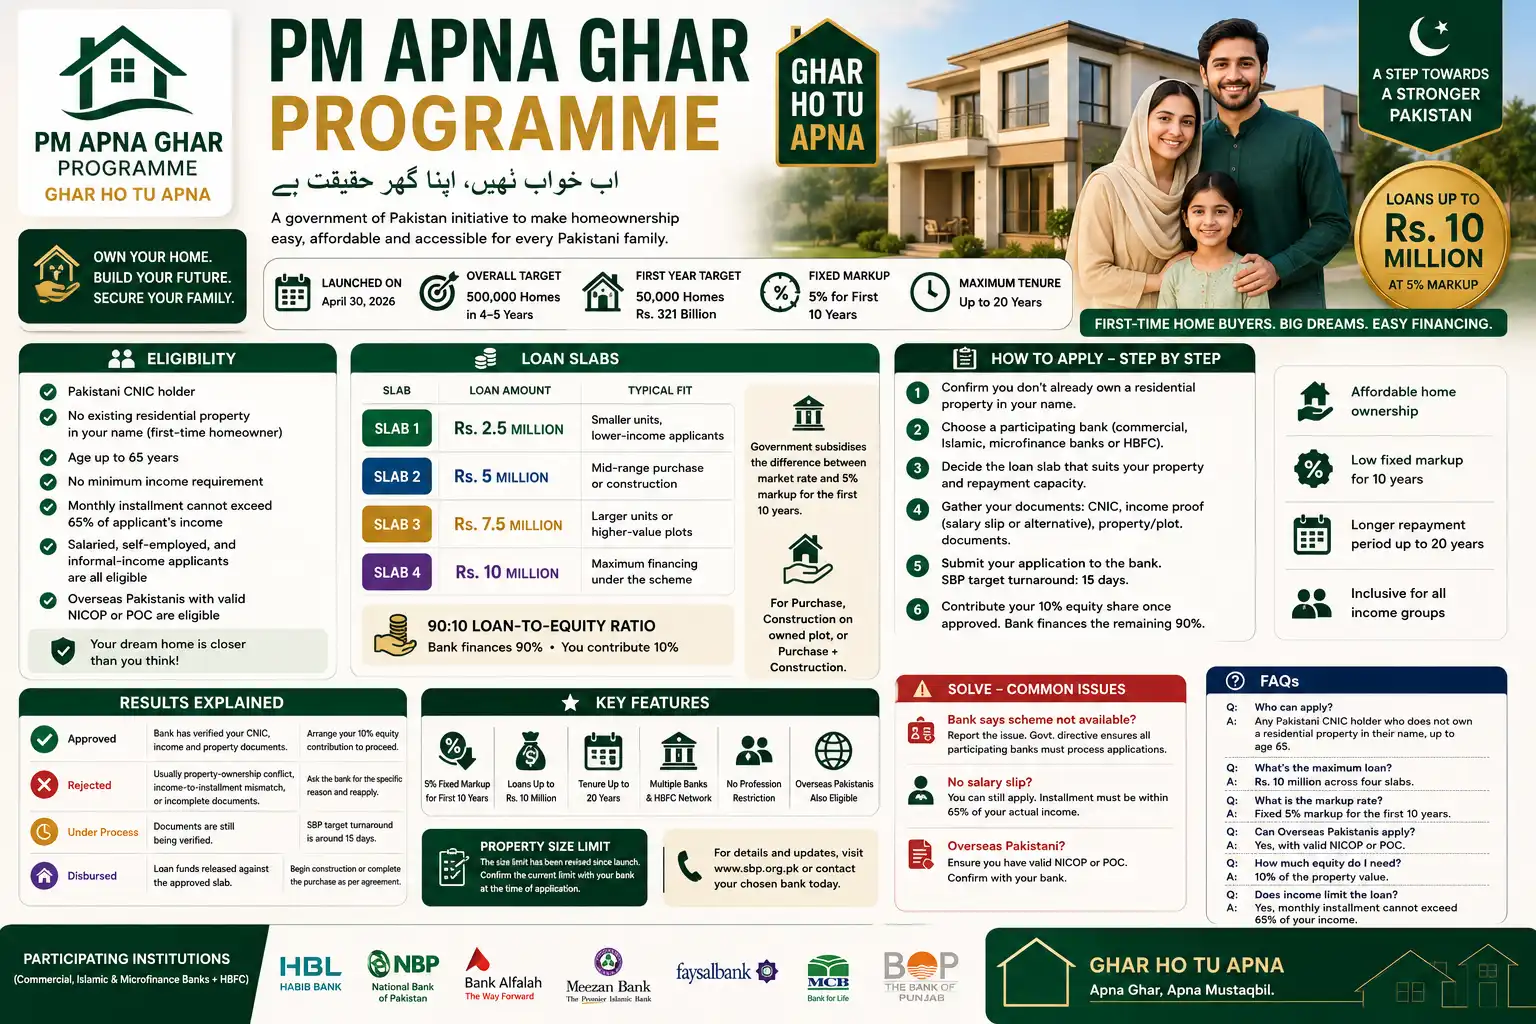
The PM Apna Ghar Programme — officially the Wazir-e-Azam Apna Ghar Programme, “Ghar Ho Tu Apna” — is the federal government’s subsidised housing-finance scheme, launched by Prime Minister Shehbaz Sharif on April 30, 2026, in Islamabad. It’s overseen by the Ministry of Housing and Works and regulated by the State Bank of Pakistan (SBP), sitting alongside BISP and the PM Youth Programme on the Federal Schemes hub, but built for first-time homebuyers rather than students or low-income cash beneficiaries. It offers loans up to Rs. 10 million at a fixed 5% markup for the first 10 years, delivered through commercial banks, Islamic banks, microfinance banks, and the House Building Finance Company (HBFC). This guide covers eligibility, loan slabs, and how the application actually moves once you submit it.
What is the PM Apna Ghar Programme
The scheme finances the purchase of a new house or flat, construction on a plot you already own, or purchase-plus-construction, aiming to move families from renting to ownership. According to Business Recorder’s reporting on the SBP’s official framework, the federal government has run this scheme through a multi-channel implementation strategy, and expanded it since launch to include Overseas Pakistanis and Non-Resident Pakistanis holding a NICOP or POC. The government has set an overall target of 500,000 financed housing units, with a first-year target of 50,000 homes backed by Rs. 321 billion, according to Profit/Pakistan Today’s coverage of the launch.
| Detail | Figure |
|---|---|
| Launch date | April 30, 2026 |
| Overall target | 500,000 housing units, over roughly 4–5 years |
| First-year target | 50,000 homes, Rs. 321 billion |
| Maximum loan | Rs. 10 million |
| Fixed markup | 5% for the first 10 years |
| Maximum tenure | Up to 20 years |
| Loan-to-equity ratio | 90:10 (bank finances 90%, borrower contributes 10%) |
Eligibility
According to the State Bank of Pakistan’s own published eligibility criteria, the core rule is simple: any Pakistani CNIC holder who does not already own a residential property in their name can apply. SBP officials have clarified that:
| Rule | Detail |
|---|---|
| Ownership status | Must be a first-time homeowner — no existing residential property in your name |
| Age | Banks accept applications from applicants up to 65 years old |
| Income | No fixed minimum income requirement; salaried and non-salaried applicants can both apply |
| Installment cap | Monthly installment cannot exceed 65% of the applicant’s income |
| Profession | No profession is excluded — SBP has explicitly confirmed this covers salaried, self-employed, and informal-income applicants alike |
| Overseas Pakistanis | Eligible if holding a valid NICOP or POC, per SBP’s revised framework |
Property size limits have been revised since launch — the scheme initially covered units up to 5 Marla or 1,360 square feet for flats, and SBP’s later framework expanded this ceiling, according to Business Recorder. Confirm the current size cap with your chosen bank at application time, since it has already changed once.
Loan Slabs
| Slab | Loan Amount | Typical Fit |
|---|---|---|
| Slab 1 | Rs. 2.5 million | Smaller units, lower-income applicants |
| Slab 2 | Rs. 5 million | Mid-range purchase or construction |
| Slab 3 | Rs. 7.5 million | Larger units or higher-value plots |
| Slab 4 | Rs. 10 million | Maximum financing under the scheme |
The government subsidises the gap between the market markup rate and the fixed 5% customer rate for the first 10 years of the loan, which is what keeps the monthly installment lower than a standard commercial mortgage.
How to Apply — Step by Step
- Confirm you don’t already own a residential property in your name — this is checked against your CNIC record.
- Choose a participating bank — commercial banks, Islamic banks, microfinance banks, and HBFC are all approved implementing partners.
- Decide which loan slab (Rs. 2.5M, 5M, 7.5M, or 10M) matches the property you want to buy or build.
- Gather your CNIC, income documentation (salary slip if salaried, or alternate income proof if not), and property documents for the plot or unit.
- Submit your application to your chosen bank; SBP-backed reforms have targeted a 15-day turnaround for approvals.
- Contribute your 10% equity share once approved, with the bank financing the remaining 90%.
Results Explained
| Status | What it means | What to do |
|---|---|---|
| Approved | Bank has verified your CNIC, income, and property documents | Arrange your 10% equity contribution to move to disbursement |
| Rejected | Usually a property-ownership conflict, income-to-installment mismatch, or incomplete documents | Ask the bank for the specific reason; a corrected reapplication is possible |
| Under process | Documents are still being verified | SBP’s target turnaround is around 15 days — if it runs well beyond that, follow up with your bank directly |
| Disbursed | Loan funds released against the approved slab | Begin construction or complete the purchase per your loan agreement |
Solve — Common Problems
If a bank branch tells you the scheme isn’t available or delays your application without explanation, that runs against the government’s own directive — the Prime Minister has publicly warned participating banks that slow processing will affect their standing under the scheme, according to reporting on the launch. If your income doesn’t come from a formal salary, don’t assume you’re ineligible — SBP has explicitly confirmed applicants without salary slips can still apply, as long as the projected installment stays within 65% of your actual income. If you’re an Overseas Pakistani unsure whether you qualify, confirm your NICOP or POC status with your chosen bank directly, since this eligibility was added after the original April launch.
In practice, banks that already run HBFC-style housing finance tend to process Apna Ghar applications faster than banks newer to housing lending, since the documentation and valuation process is broadly similar to what they already do for standard mortgages.
FAQs
Who can apply for the PM Apna Ghar Programme?
Any Pakistani CNIC holder who does not already own a residential property in their name, generally up to age 65, can apply — there is no fixed minimum income requirement.
What’s the maximum loan amount?
Rs. 10 million, available across four slabs (Rs. 2.5 million, 5 million, 7.5 million, and 10 million), depending on the property’s value and your repayment capacity.
What markup rate applies?
A fixed 5% markup for the first 10 years of the loan, with the government subsidising the difference between that rate and the market rate.
Can Overseas Pakistanis apply?
Yes. Overseas Pakistanis and Non-Resident Pakistanis holding a valid NICOP or POC became eligible under SBP’s revised framework after the scheme’s initial launch.
How much equity do I need to contribute myself?
The loan-to-equity ratio is 90:10 — the bank finances 90% of the property cost, and you contribute the remaining 10%.
Does my monthly income limit how much I can borrow?
Yes. SBP has set a rule that your monthly installment cannot exceed 65% of your income, which effectively caps your loan slab based on what you earn.