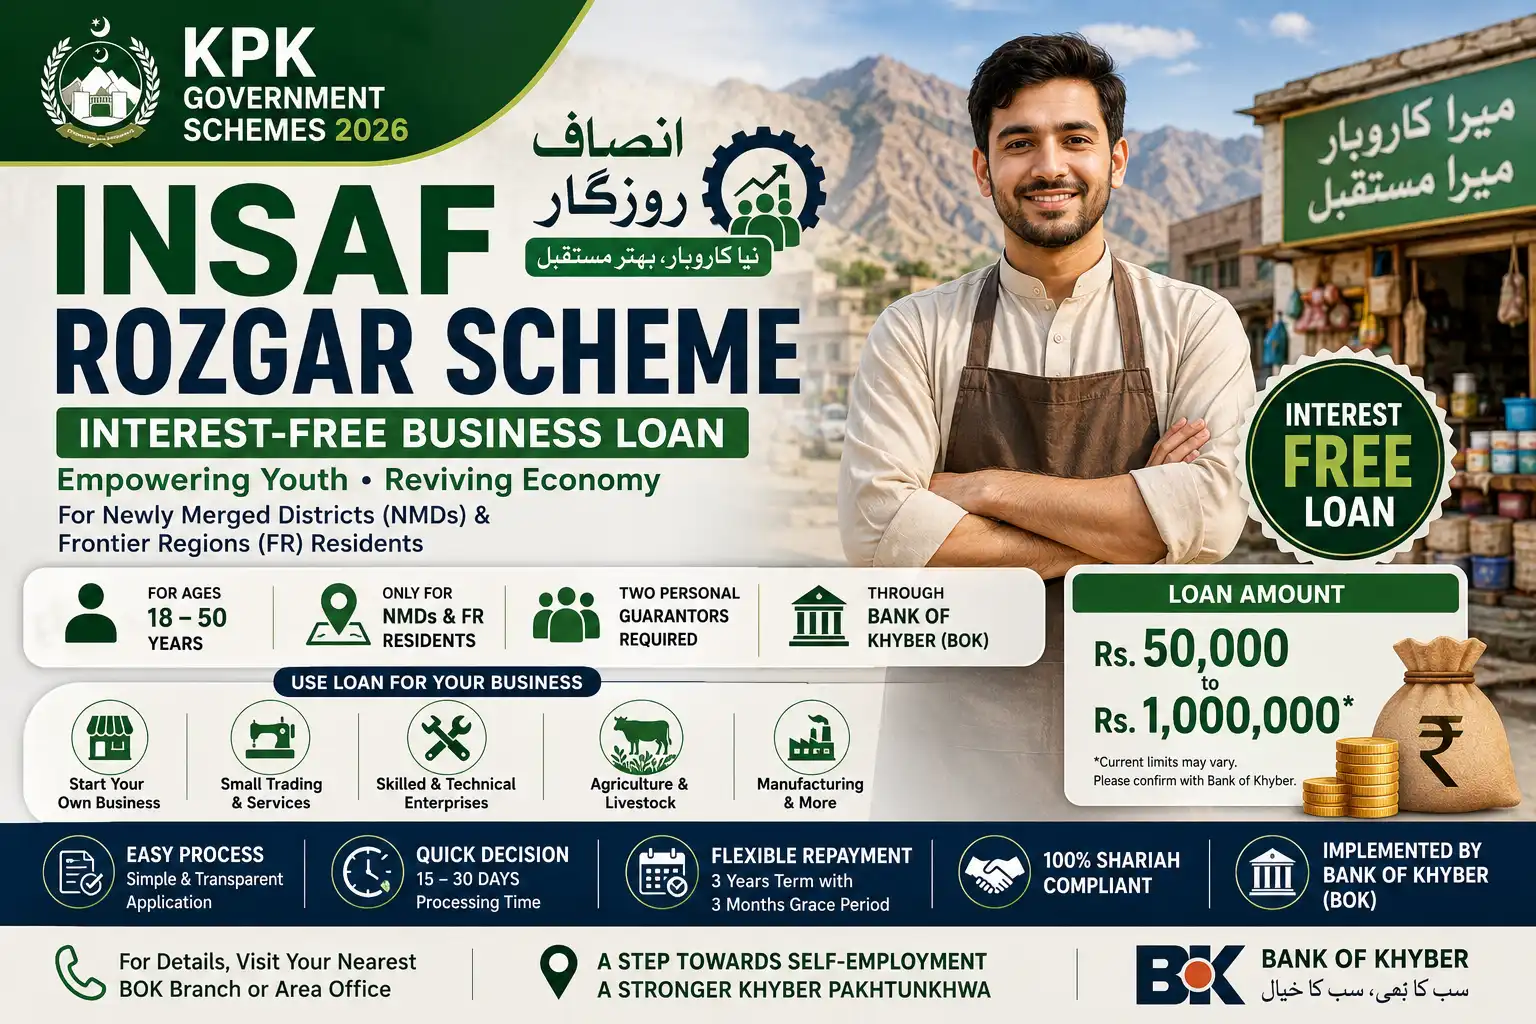
Insaf Rozgar Scheme Khyber Pakhtunkhwa ke Newly Merged Districts (NMDs) ke residents ko interest-free business loan deta hai, jo micro-scale enterprises shuru karne ya support karne ke liye hai. Yeh scheme KPK Government Schemes 2026 ke Youth Employment & Business Loans category ka hissa hai aur Bank of Khyber (BOK) ke through issue hota hai. Yeh guide eligibility, required documents, aur agar application reject ho to kya karna hai — sab cover karti hai.
Insaf Rozgar Scheme Kya Hai
Yeh scheme specifically Newly Merged Districts aur FR (Frontier Regions) ke residents ke liye hai, jo terrorism-affected areas mein economic activity revive karne ke liye design ki gayi hai. Loan un logon ke liye hai jo apni micro scale enterprise shuru karna chahte hain — jaise unemployed individuals, small traders, ya skilled institutes se pass out honay wale trainees. GoKP development programs se pass out candidates ko priority di jati hai.
Eligibility
| Requirement | Detail |
| Residency | Newly Merged Districts (NMDs) ka permanent resident hona zaroori |
| Address duration | Kam az kam 2 saal usi address par resident hona zaroori |
| Identity | Valid Computerized CNIC |
| Age | 18 se 50 saal |
| Business idea | Doable, viable business idea, applicant ki skills se relevant |
| Guarantors | Do Personal Guarantors (PGs) zaroori — kam az kam ek guarantor Government employee ho, BPS 07 ya us se upar |
Priority skilled GoKP development programs ya affiliated institutes se pass out candidates ko milti hai, saath hi unemployed workforce aur small traders ko bhi.
How to Apply
- Bank of Khyber ki website ya nearest Area Office/BOK branch (NMD ya FR region mein) se application form hasil karein.
- Form ko complete karein aur required documents ke saath submit karein.
- Required documents mein shamil hain: do passport-size photos (applicant aur guarantors ke), degree/diploma/skill certification ki attested copy (agar applicable ho), government guarantor ki salary slip, concerned department se BPS confirm karne wala Letter of Comfort, aur private guarantor ki income proof stamp paper par undertaking ke saath.
- Bank application review karega — decision aam tor par 15-30 din mein milta hai.
- Approval ke baad, loan agreement sign karein, 10% down payment pay karein.
- Baaqi 90% installments mein disburse hota hai.
Har step apne aap mein zaroori hai — incomplete documentation review process ko significantly delay kar deti hai.
Results Explained
Agar application approve ho jaye, to applicant ko loan agreement sign karna hota hai, 10% down payment pay karna hota hai, aur baaqi 90% installments mein milta hai. Naye enterprises ke liye 3 saal ka repayment term hota hai, jismein 3 mahine ki grace period shamil hai. Agar reject ho, to sabse aam wajah incomplete guarantor documentation ya weak business plan hoti hai.
Payment / Benefit Details
Loan interest-free hai. Historical reporting ke mutabiq loan amount Rs. 50,000 se Rs. 1,000,000 tak hoti hai, technical skills wale applicants ke liye alag range aur non-technical ke liye alag — lekin yeh figures purani (2019-era) reporting se hain aur current loan limits Bank of Khyber se directly confirm karni chahiye. Actual loan size business plan ki assessment par depend karti hai, prudent banking practices ke mutabiq.
Solve — Agar Application Reject Ho Ya Masla Aaye
- Guarantor requirement poori na ho: Kam az kam ek guarantor Government employee (BPS 07+) hona zaroori hai — is criteria ko pehle confirm kar lein apply karne se pehle.
- Business plan weak samjha jaye: Ek detailed, realistic business plan jo aapki skills se directly relevant ho, approval chances behtar karta hai.
- Documents incomplete hon: Poori list — photos, certifications, salary slips, Letter of Comfort, income proof — submit karne se pehle dobara check karein.
- NMD residency proof na ho: Kam az kam 2 saal ki residency proof zaroori hai — agar recent move hua ho, to eligibility abhi na ho sakti.
In practice, sabse zyada rejections guarantor documentation incomplete hone ki wajah se hote hain — apply karne se pehle apne guarantors se poori documentation ikatthi kar lena behtar hota hai.
What’s Next
Application submit karne ke baad 15-30 din ka wait karein bank ke decision ke liye. Approve hone par turant loan agreement sign karein aur down payment arrange karein taake disbursement process shuru ho sake.
FAQs
Yeh scheme kis ke liye hai?
Yeh sirf Khyber Pakhtunkhwa ke Newly Merged Districts (NMDs) aur FR regions ke permanent residents ke liye hai. Poore KP ke residents is specific scheme ke liye eligible nahi.
Maximum loan amount kitna hai?
Historical figures Rs. 50,000 se Rs. 1,000,000 tak batate hain, lekin current loan limits Bank of Khyber se directly confirm karni chahiye kyunke yeh figures purani reporting se hain.
Guarantor kaun ho sakta hai?
Do guarantors zaroori hain, jismein se kam az kam ek Government employee hona chahiye, BPS 07 ya us se upar. Doosra guarantor private ho sakta hai, lekin unki income proof stamp paper par undertaking ke saath deni hoti hai.
Application kitne din mein process hoti hai?
Bank of Khyber aam tor par 15-30 din mein decision deta hai. Approval ke baad loan agreement aur down payment ki process shuru hoti hai.
Repayment period kitna hai?
Naye enterprises ke liye 3 saal ka term hota hai, jismein 3 mahine ki grace period shamil hai. Loan interest-free hai.